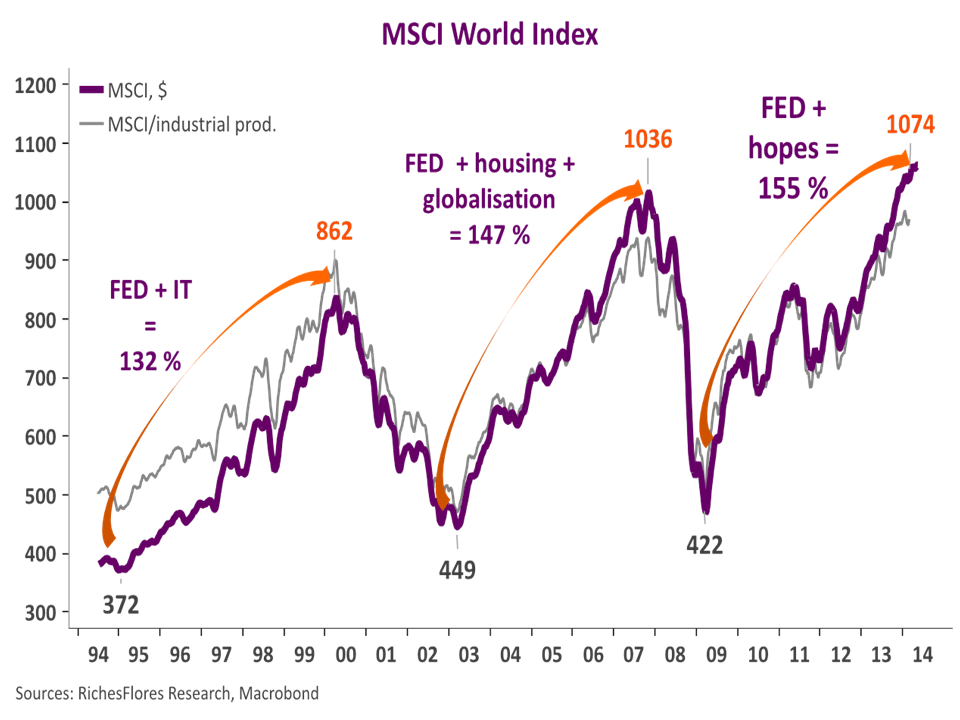
Our contrarian outlook for a global growth slowdown starting in the second half calls for caution in terms of asset allocation
Global growth slowing next year to 2.8% versus 3.2% this year
- U.S. growth is failing to take off: real estate prices have increased too fast, thus squelching the recovering in the construction industry, growth inertia in services continues to hurt the job market, weak productivity growth has failed to provide the necessary boost to investment that would extend the cycle. Growth disappoints and will not exceed 2% this year or next year.
- Deflation is settling into the euro area and is propagating to the countries in the northern part of the currency union. Following the favorable boost from the economic recovery, keeping the momentum going proves difficult due to the deteriorating export outlook. Germany is not playing its role as an economic engine, other countries are not recovering. Next year, growth will fall to 0.9%, after 1% this year.
- The situation for emerging markets suffers from the negative influence of the Chinese economy: export markets are drying up, soft demand for commodities and devaluation of the Renminbi. Imbalances and chronic shakiness increase the temporary instability. The Russian economy is tipping into a recession, Brazilian growth falls after the uptick from the World Cup, the effects of Indian reforms are diluted by a difficult economic situation.
New bond rally
- The Fed will not see « tapering » through to the end; key rates will stay at zero. The 10Y will decrease to 2-2.25% before the start of 2015.
- The ECB will embark on a long journey of non-conventional monetary policy. Long rates will fall, following the bund, whose 10Y yield will fall to 1-1.25% before early 2015. Interest rate gaps between countries in southern Europe and the German bund will stabilize before widening again in 2015.
- The risk of deflation increases the world over, commodity prices fall back as instability increases. Brent drops to under $90/b.
Growing instability on the forex markets
- The Fed’s strategy shift contradicts the ECB easing, the euro does not fall.
- The BoJ roars back to life after the failure of Abenomics, the yen tumbles in 2015.
- Forex risk increases in EMs, particularly in Asia where the currency war pits the Japanese against the Chinese.
Downturn in the equity markets
The change in outlook weighs on earnings forecasts and cyclical stocks.
The S&P recedes to 1,600, the EuroStoxx returns to 300 points. Industrial equities take a hit, with the DAX squarely in the crosshairs.